


Brazil, Spain, France, Poland, Singapore, Bulgaria and Slovenia all broke records in September. So did the US, for one final month, as Mr Big and Beautiful guts the Inflation Reduction Act.
Let’s dive in. Don’t forget you can always explore the data yourself…
The numbers, in brief
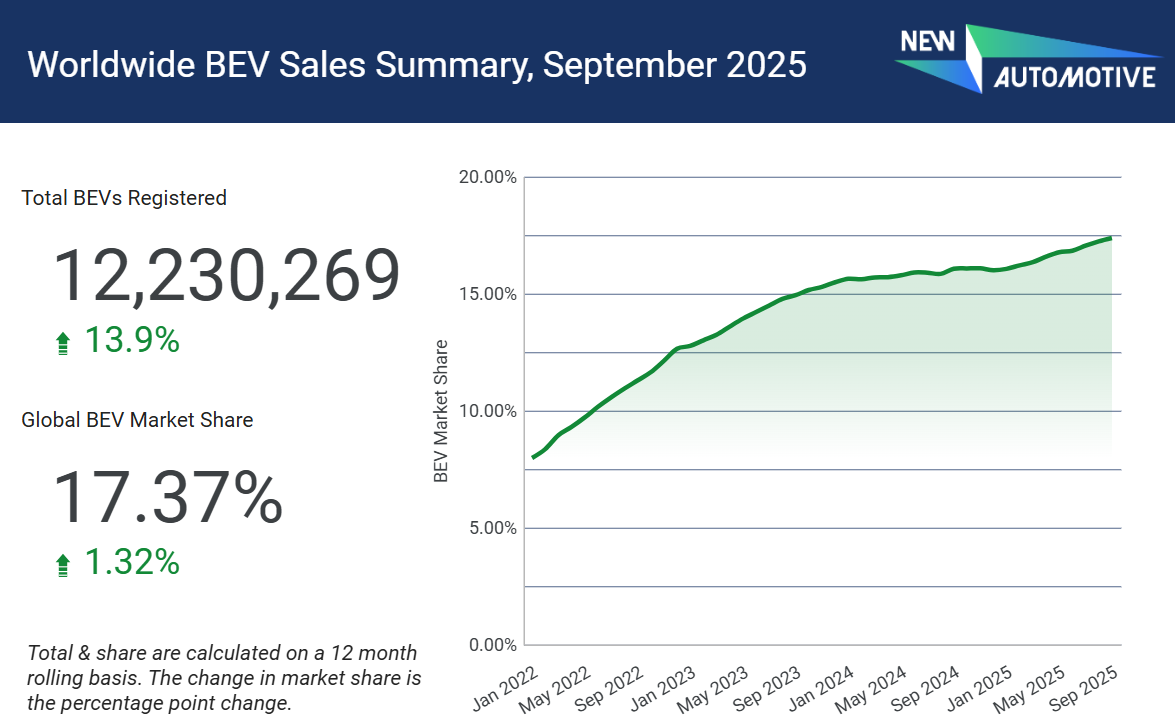
First, the top-line figures. The global market is still growing. New AutoMotive’s preferred metric to gauge the health of global battery electric (BEV) sales is a rolling 12 month total (which avoids any seasonal fluctuations in the highly seasonal auto market). BEV registrations grew by 13.9% on this basis - compared with a rise of 5.3% for the car market as a whole, meaning that battery electric accounted for 42% of registration growth globally. The market share of BEVs hit a new all-time high of 17.4% this month.
31 of the 42 markets we monitor saw an increase in EV registrations on a year-on-year basis, whilst 30 saw an increase on September 2024 levels. The 10 fast growing markets on a month-by-month basis are shown below.
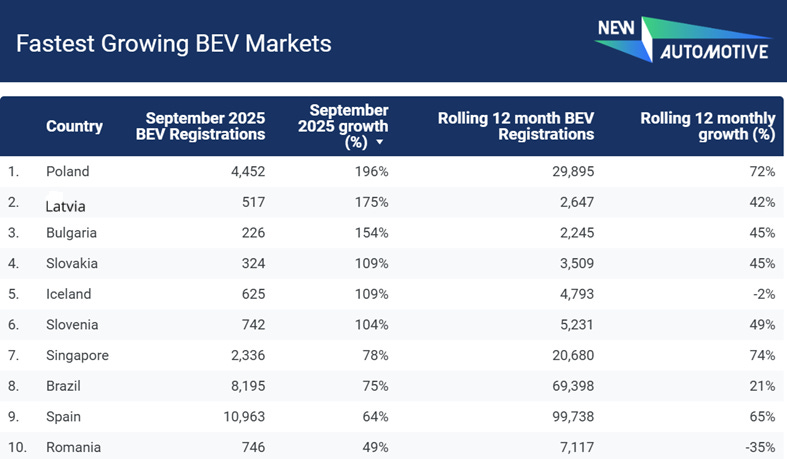
Most of these countries are smaller markets - however Spain is the fourth and Poland the fifth largest car market in the EU, whilst Brazil is by far the largest South American economy. And all 10 are showing sustained year-on-year growth, with the exception of Romania (still suffering an extended hangover from a switch-off in incentives) and Iceland (labouring under an inequitable road-pricing system).
The top 10 markets remain unchanged on last month, when measured on a rolling 12 monthly basis, although France has retaken 5th place from Türkiye for the month of September.
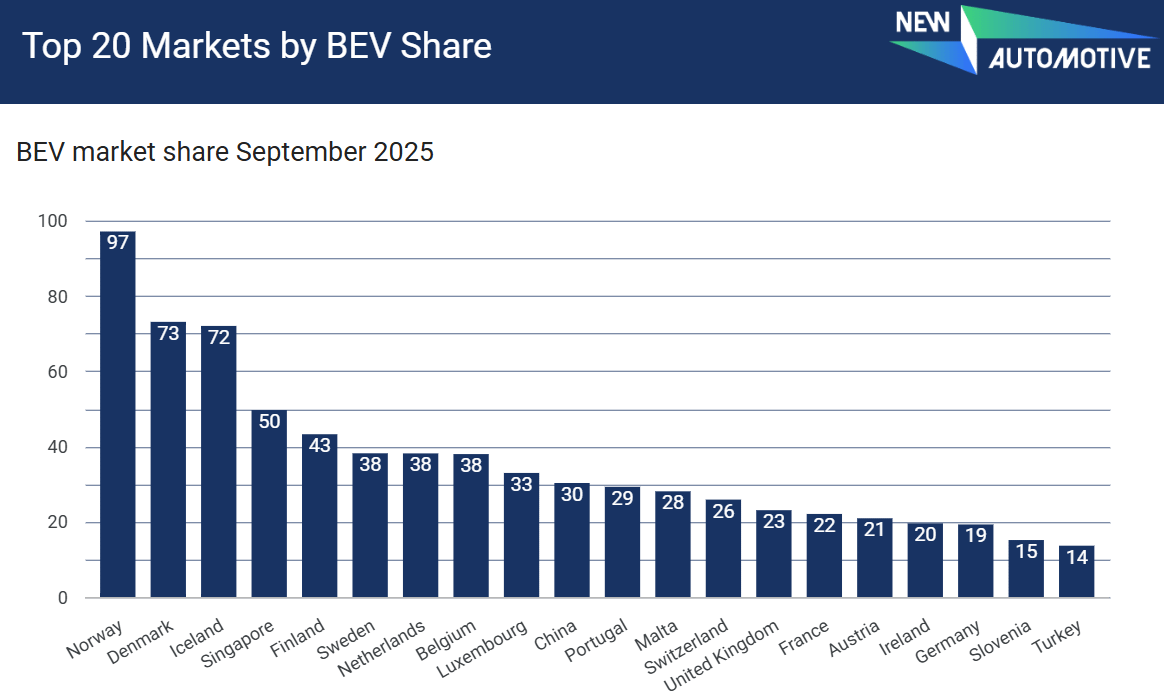
The top 20 markets by BEV market share for the month of September 2025 saw some movement in the smallest countries where market shares are volatile. Malta and Luxembourg rose, whilst Ireland fell back. Amongst larger economies, France and Germany edged forward, whilst Türkiye fell back (see Continent Summaries below).
Global Roundup
Asia
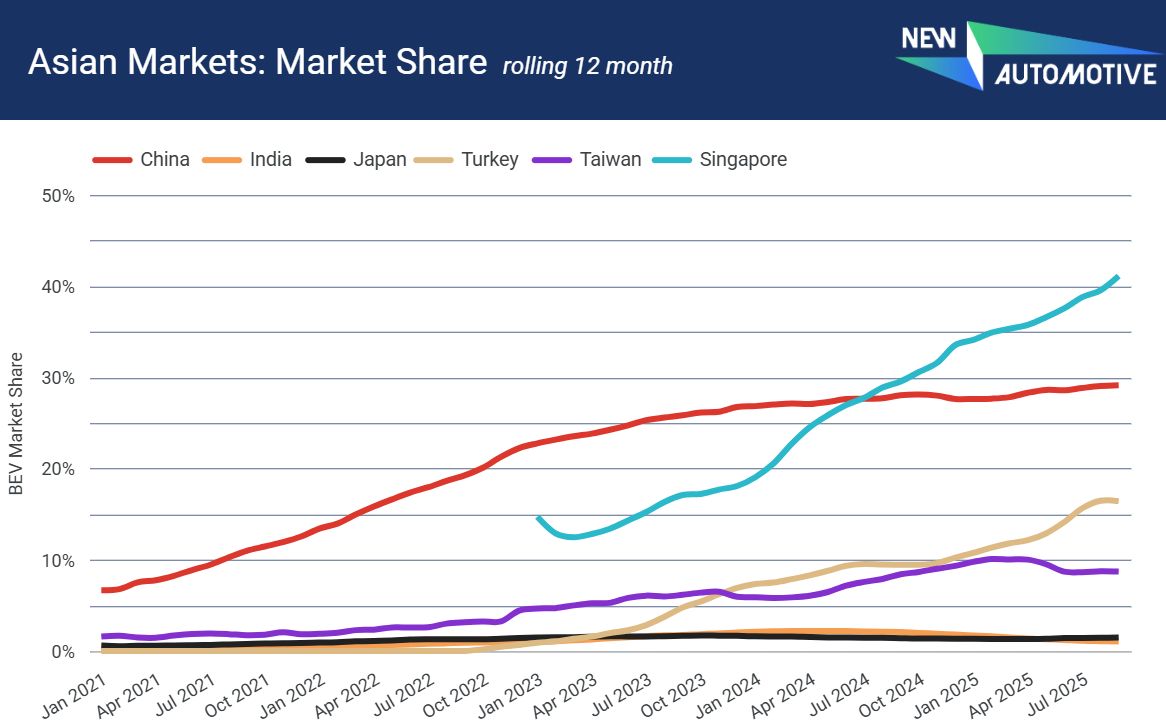
Battery electric registrations in China were up 9% on the same month last year. However market share is showing clear signs of plateauing - dipping marginally to 30% in September, only 1 percentage point up on the same month last year. PHEV market share was also flat, at 14%. Last month we noted the apparent ending of state subsidies in some Chinese provinces, and this appears the most likely reason - there is no fixed 55% of the public who are unwilling to switch, as several Nordic economies have shown.
Singapore has shown the same thing, by moving further ahead as the leader in Asia, hitting 50% battery electric market share for the first time last month. Now the relentless march of battery electric cars is gobbling up the market share of hybrids. Last month the latter’s market share fell to 32%, the lowest since we began to collect data 3 years ago. Petrol is flatlining in the 14-16% range, and diesel is now - wisely for the densely populated city state - banned.
The car market in Türkiye continues to take stock following the withdrawal of some EV incentives. Registrations were down to 14% in September, a level last seen in April. However, the reversion of registrations to the pre-withdrawal level is a cause for hope. Demand is clearly still there, with or without the incentives, and Türkiye is still in the middle of the pack on BEV market share when measured against EU member states, despite being poorer than all of them. The fundamentals for Türkiye - as a car-making country investing heavily in the transition - are good, and we can expect the recovery to begin next month.
Taiwan’s battery electric market continues to yo-yo, but this September’s market share of 14% was the highest since June 2024 and the second highest of all time. Petrol has hovered at 51-52% for the past 3 months, whilst diesel - at 1-2% market share for the whole of 2025 - is at death’s door.
In Japan the zombie EV market is twitching - slightly. BEV market share reached 1.95%, the second-highest in the past 24 months. However we need to curb our enthusiasm. At the current rate, Japan won’t hit an average battery electric market share of 2% until 2030, well over a decade after most of the other developed economies reached this marker.
India also continues its own sideways/backwards journey to decarbonisation of 4 wheelers. The dash to alternative fuels such as compressed national gas has resulted in such vehicles now accounting for 42% of new registrations, almost 3 times the proportion last September. We don’t have time any more for “transitional technologies” that push out vast numbers of only marginally cleaner vehicles to clog the roads for another decade. Modi’s commitment to reach 100% zero emission vehicles by 2040 (from the current 1%) is looking more and more hollow.
The Americas
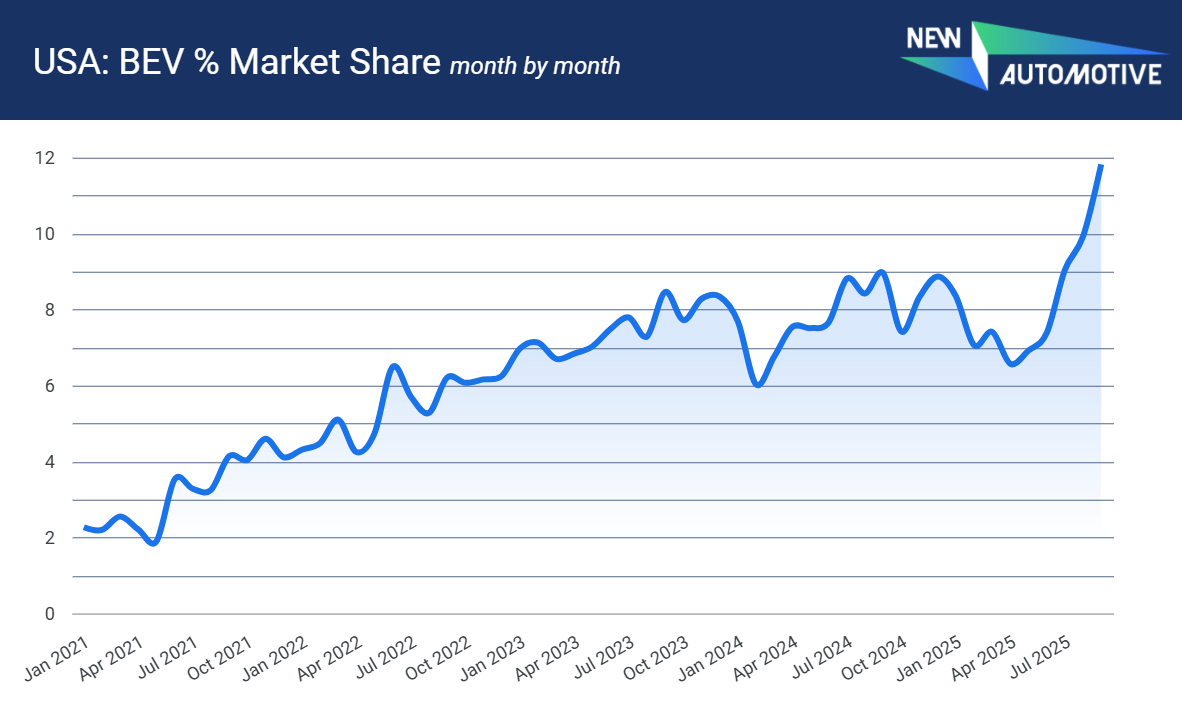
The United States hit an all-time high of 11.8% battery electric market share in September, the final month that the Biden-era tax credit will be available. No-one is expecting sales to reach that level in future months. The traditional consumer response to any deep cut is a cratering of sales - so if battery electric exceeds the 6% market share which EVs were achieving in late 2022 before the Inflation Reduction Act came into force, it will be a win.
Meanwhile, momentum continues to build in Brazil where an all-time high of 8,200 battery electric cars were registered in September. Market share was the 2nd highest ever, at 3.66%. The 12 month rolling market share - a lagging indicator in such a fast growing market - has been climbing steeply since the beginning of the year. Chile had a weaker month, with 1.8% BEV market share in September. However the trend is clearly still upward.
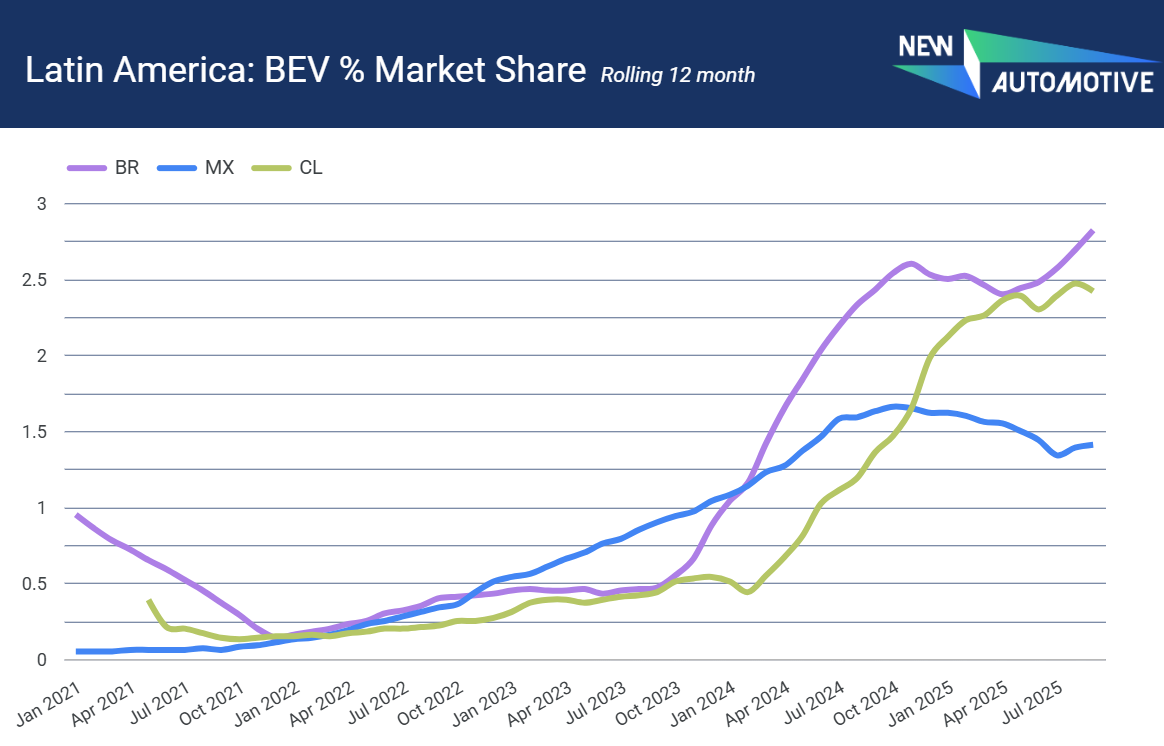
Elsewhere Mexico’s battery electric market share reached 1.7% last month, the second highest in 2025, but still well down on levels reached before November 2024 when our friend to the north was elected. Trump’s concerns about backdoors to the USMCA trade agreement giving American consumers the horrors of the cars they want at a good price has resulted in firms like BYD putting factory plans on hold. This means any future EV growth is likely to be import-led, with limited immediate benefit to the Mexican economy. This in turn makes it unattractive for the Sheinbaum government to invest.
Europe
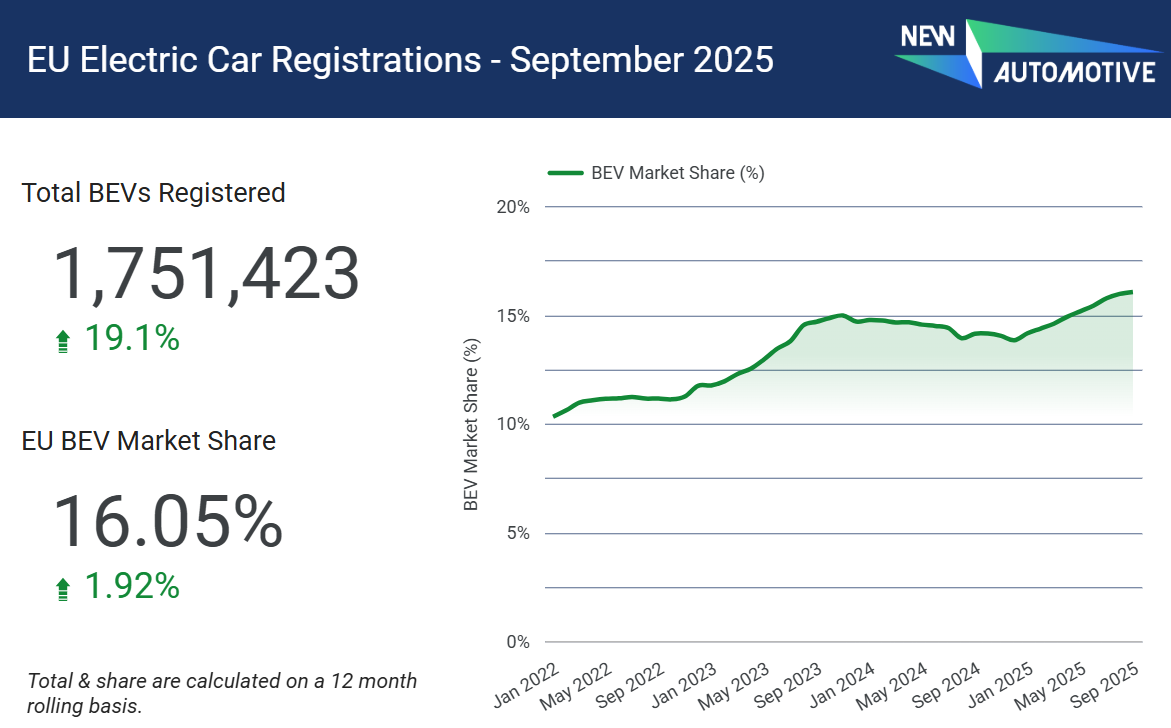
Across the EU and the rest of Europe, Germany, Austria, Portugal, Hungary and Ireland have all seen rolling 12 month growth of more than 20%. Norway, the UK, Greece and Cyprus have all achieved more than 30%. Meanwhile Denmark, Slovenia, Slovakia, Bulgaria and Latvia have all scored 40% increases, whilst Poland, Spain and Czechia have hit more than 50% on the past 12 months.
For Poland, the sixth largest EU car market, September saw an all-time high for battery electric market share of 9%, Bulgaria reached 6% for the first time, whilst Slovenia reached both a country-level and Eastern Europe-wide high of 15%.
Interestingly, Bulgaria and Slovenia abstained on the original vote to phase out internal combustion engine cars by 2035, whilst Poland voted against. When the consumer facts change, policymakers need to change their minds.
And that is already happening in Poland, with new investment in battery production, the introduction of incentives, and a big shift to a cleaner grid, with 34% of generated energy coming from low carbon sources last year, almost double the level of 2021.
Many of these are of course smaller markets. Germany, France, Spain and Italy account for two-thirds of EU registrations, whilst the UK is by far the largest market outside the EU. Let’s dive into the big five.
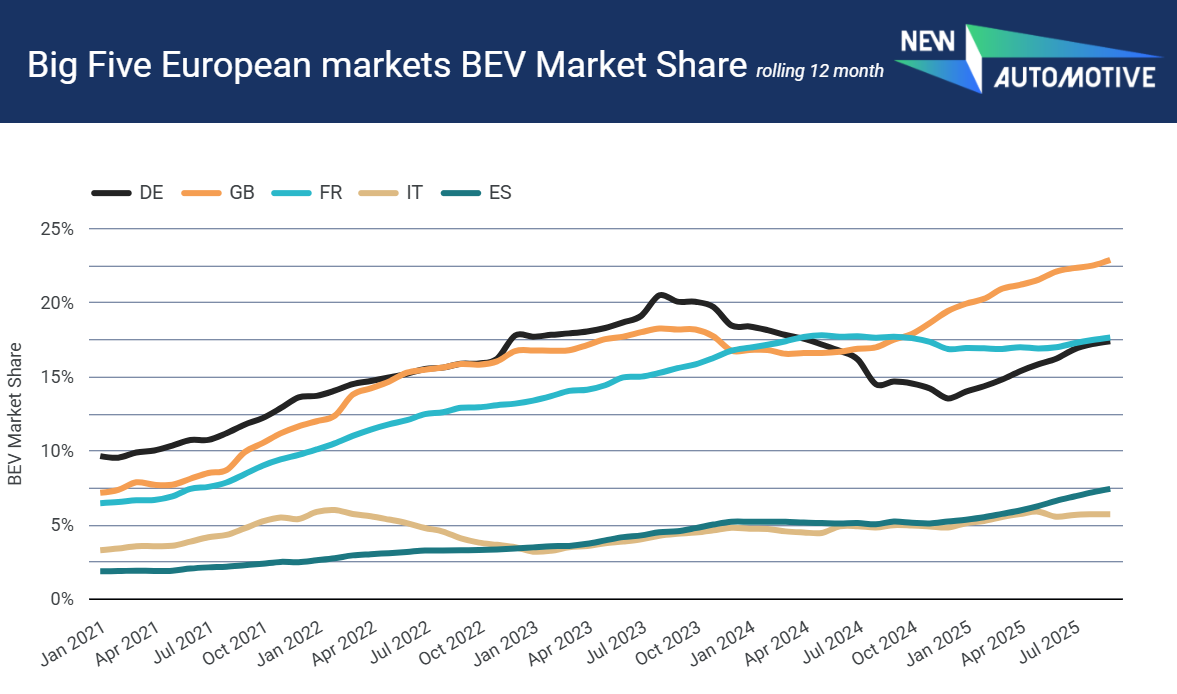
After a late 2023 and early 2024 lull caused by political uncertainty from the ruling Conservative party, United Kingdom registrations have boomed under Labour, outpacing Germany and France with a 35% growth in market share over the past 12 months.
Demand in Germany continues to recover after the tribulations of stop-start (mostly stop) policy initiatives, reaching 19.3%, the biggest market share since December 2023. Not quite a full bounce back, but at least a bounce. And whilst the challenges with PHEVs have been well documented, German consumers are clearly taking an interest - registrations reached a record 11.8% last month, meaning vehicles with a plug accounted for 31% of new registrations, the highest for more than 2 years
Not yet visible in the 12 month rolling average, registrations in France ticked up in September with the relaunch of social leasing on a sounder financial footing. BEVs reached 22.1% market share, an all-time high. The last time France had an all-time high was December 2023. Time will tell whether this is a blip caused by pent-up demand, or whether we’re at the point of long-awaited sustained growth in the EU’s second largest market.
Until Spring of this year, Spain and Italy were laggards together, flatlining between 5 and 6% market share for the foreseeable. But Spain’s fast growing car market has broken out of that range and last month hit 10.6% market share, the first time ever that it has reached double figures. Once dominant diesel is down to 14%. With plentiful supplies of zero carbon electricity and growing investments in the battery supply chain, Spain has so much to gain from the transition. That’s why, alongside France, they’re lobbying to retain the 2035 phase out date on internal combustion engines, restoring incentives and straightening out their charging network. Meanwhile Italy coasts at 6%.
Top manufacturers
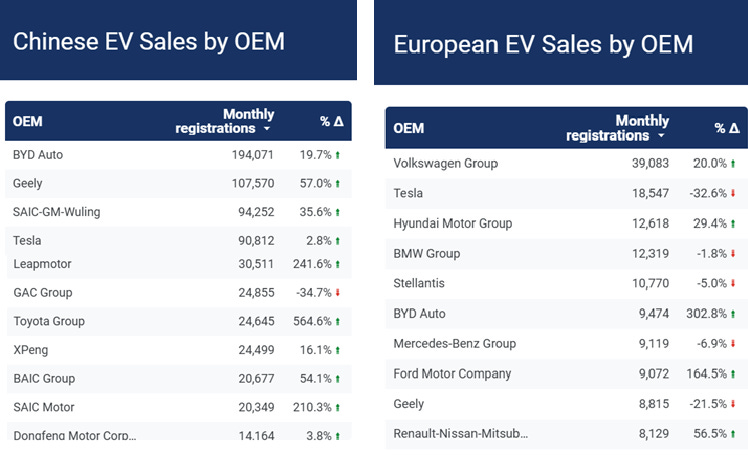
Finally, let’s take a brief look at manufacturer data for China alongside 9 European markets, including Germany, the UK, the Netherlands, Spain and Italy.
Tesla registrations stabilised in China in September, and are ‘only’ down 10% year-on-year. However the cloud on this silver lining is that BYD are up 25%, SAIC and Wuling (a joint venture between SAIC and GM) are up 76% and Geely have moved forward a staggering 175% year-on-year.
Helped by their first performance- and price-competitive new EVs, Toyota were 7th - the first non-Chinese firm - other than Tesla - to figure in the top 10 in 2025. Not every overseas player is packing up and going home from China. This is good news for Chinese consumers and great news for the transition. Now we just need Toyota to sell these much improved and price-competitive EVs in some other countries.
With a much more limited range of EVs in Europe, Toyota languishes in 12th place across the European countries for which we collect data. Volkswagen Group are still far in front with growth of 20% on September 2024 (up 65% year-on-year), whilst second-placed Tesla are down 33% on September 2024 and 23% year-on-year.
Latecomers to the switch Ford are up to 8th, but the biggest growth is seen by BYD which, despite the swingeing tariffs on Chinese-made BEVs, took 6th place, its highest ever position. Working with only one-hand tied behind its back appears not to be a big enough handicap for BYD.
The manufacturers’ trade body is probably thinking about building a bigger begging bowl. But rather than the endless drip-drip of talking down the market, talking up imaginary technologies and hoping for the goalposts to move, they can advocate for the transition, endorse policy stability, and learn from the countries and firms where registrations are surging.
Here’s hoping.
Global EV Tracker monitors passenger car registrations from 40+ markets representing over 80% of global car registrations, updated monthly. The countries we covered in this bulletin are: China, United States, India, Germany, Japan, Brazil, United Kingdom, France, Mexico, Italy, Spain, Türkiye, Poland, Belgium, Taiwan, Netherlands, Sweden, Austria, Portugal, Czechia, Switzerland, Denmark, New Zealand, Norway, Greece, Romania, Hungary, Ireland, Slovakia, Finland, Croatia, Slovenia, Singapore, Luxembourg, Bulgaria, Lithuania, Estonia, Latvia, Cyprus, Iceland, and Malta.